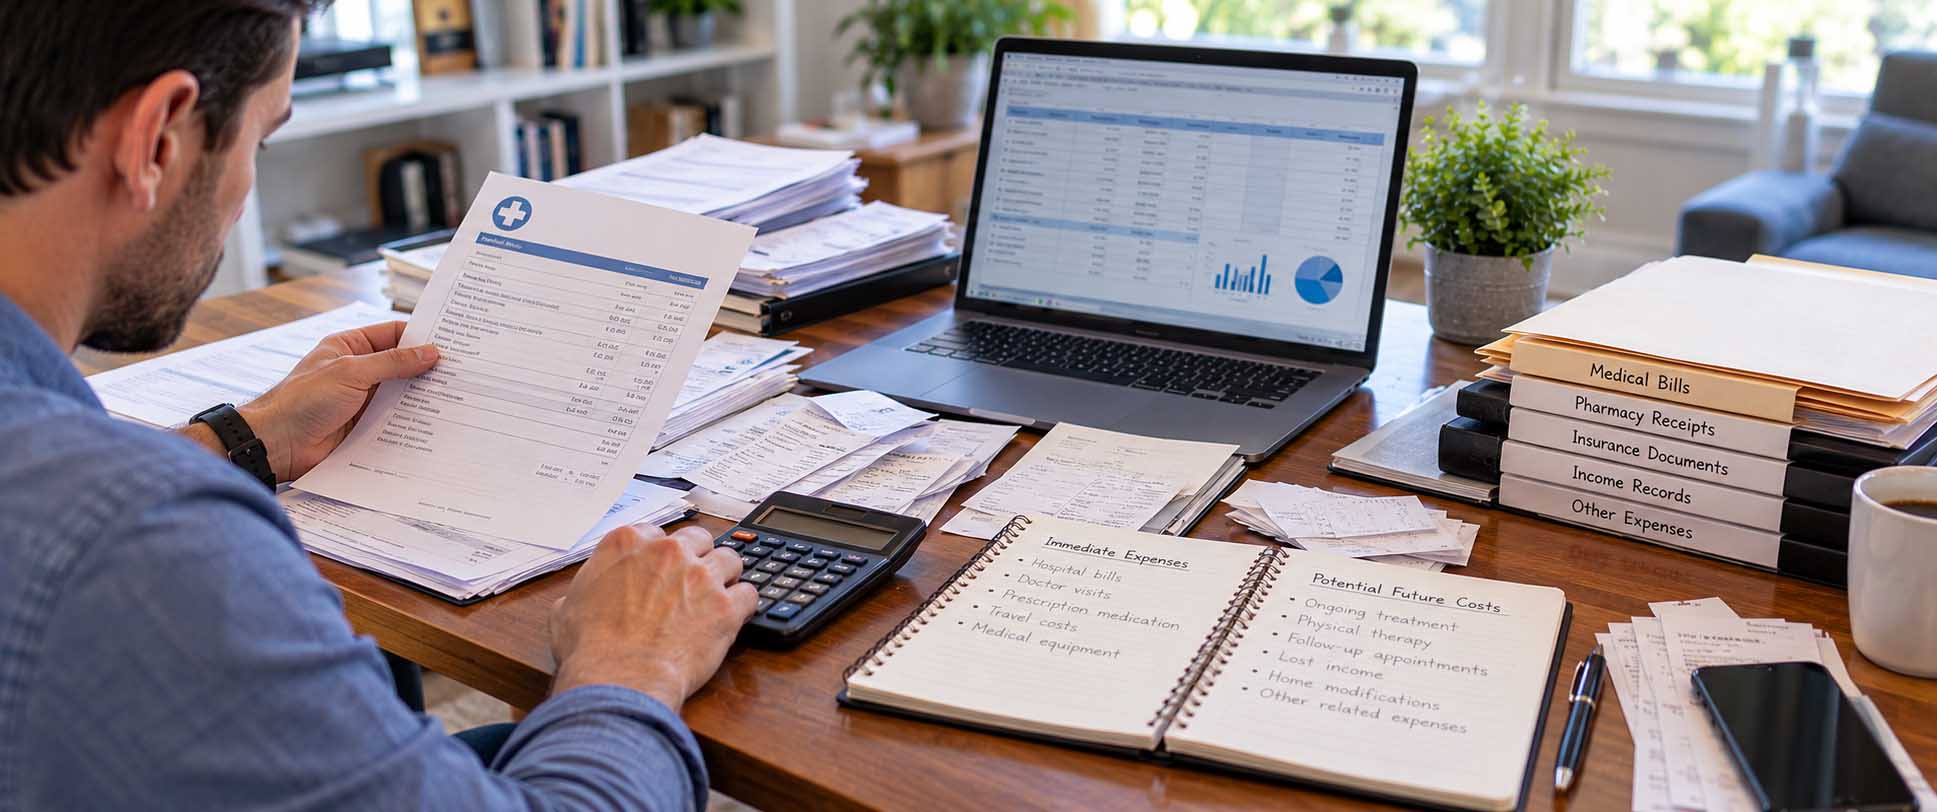
Economic damages after an accident are measurable financial losses that an injured person may seek to recover through a personal injury claim. These losses can include medical expenses, lost earnings, reduced earning capacity, and other accident-related costs supported by appropriate evidence.
Unlike compensation for pain and suffering, economic damages focus on financial consequences that individuals can generally document or reasonably calculate.
However, not every expense automatically qualifies for compensation.
The amount recoverable depends on the circumstances, applicable law, available evidence, and whether the losses have a legally sufficient connection to the accident.
Understanding these distinctions can help injured individuals organize their financial records and evaluate potential claims.
What Are Economic Damages After an Accident?
Economic damages are financial losses resulting from an injury or other legally recognized harm.
In personal injury cases, they generally involve expenses already incurred and certain future financial losses that a claimant can establish with reasonable certainty.
For example, someone injured in a vehicle collision may require emergency medical treatment, physical therapy, and time away from work.
These consequences may create identifiable financial losses.
However, establishing their value requires more than simply estimating the total cost of the accident.
Relevant records must support the claimed amounts and their connection to the injuries.
Common Types of Economic Damages in Injury Claims
Different accidents create different financial consequences.
The following categories frequently arise in injury-related claims.
Medical Expenses After an Injury
Medical costs may represent a significant portion of an injured person’s financial losses.
Depending on the circumstances, these expenses may include:
- Emergency medical treatment
- Hospital services
- Diagnostic imaging
- Specialist appointments
- Prescription medications
- Physical rehabilitation
- Medically necessary equipment
- Follow-up treatment
However, the recoverability of particular expenses depends on the applicable legal rules and supporting evidence.
Lost Income and Missed Work
An injury may prevent someone from working temporarily.
Lost income can include earnings that the individual would otherwise have received during the relevant period.
For example, an employee recovering from an accident may miss several scheduled workdays.
Payroll records, employer statements, and other documentation may help establish the resulting financial loss.
Self-employed individuals may need additional business records to demonstrate income changes.
Reduced Future Earning Capacity
Some injuries affect a person’s ability to earn income in the future.
This differs from wages already lost.
Reduced earning capacity concerns the financial impact of limitations on future employment opportunities or work performance.
For example, an injury may prevent someone from returning to physically demanding employment.
However, estimating future losses may require vocational, economic, or medical evidence.
How Are Economic Damages After an Accident Calculated?
Calculating financial losses generally begins with identifying documented accident-related expenses and income changes.
Past expenses may be supported by invoices, receipts, payment records, and employment documentation.
Future losses require a different approach because they involve reasonable projections rather than completed transactions.
For example, anticipated medical treatment may depend on professional evaluations concerning the person’s ongoing needs.
Similarly, future earning losses may require consideration of employment history, work limitations, and expected career opportunities.
Therefore, calculations should reflect reliable evidence rather than unsupported assumptions.
Economic Damages Under New York Personal Injury Law
New York personal injury claims may involve several categories of economic loss, depending on the nature of the accident and applicable legal requirements.
For example, motor vehicle injury claims can involve New York’s no-fault insurance system, which provides certain benefits subject to statutory conditions and coverage limits.
The New York State Senate’s publication of Insurance Law § 5102 defines terms relevant to basic economic loss and first-party benefits under the state’s motor vehicle insurance framework.
However, no-fault benefits and damages recoverable through a negligence lawsuit are not necessarily identical.
Individuals researching personal injury legal guidance can review the legal services offered by Siben & Siben, LLP, a law firm based in Bay Shore, New York.
For someone injured in Nassau County or Suffolk County, discussing the applicable insurance and liability rules may help clarify which financial losses could be recoverable.
An individualized evaluation remains important because the legal framework varies by accident type.
What Evidence Supports an Economic Damages Claim?
Accurate documentation can make financial losses easier to evaluate.
Useful records may include:
- Itemized medical bills
- Pharmacy and treatment receipts
- Pay statements
- Employment attendance records
- Tax returns when relevant
- Insurance benefit statements
- Rehabilitation expense records
- Professional evaluations of future needs
Whenever possible, injured individuals should preserve records in their original form.
They should also distinguish amounts billed, amounts paid, and outstanding balances.
These figures may have different significance depending on the applicable legal and insurance rules.
Economic Damages vs. Non-Economic Damages
Economic damages concern measurable financial losses, such as treatment costs and lost earnings.
Non-economic damages concern injuries that do not have a direct financial price, such as physical pain and certain forms of emotional suffering.
For example, a person recovering from a serious injury may experience both medical expenses and substantial physical discomfort.
Although these consequences arise from the same accident, they belong to different compensation categories.
Therefore, each category requires an appropriate legal and evidentiary assessment.
Can Future Economic Damages Be Included in a Claim?
Future financial losses may be recoverable when sufficient evidence and applicable law support them.
For example, a serious injury may require continuing rehabilitation or medically necessary assistance.
However, the claimant must establish anticipated expenses with an appropriate degree of certainty.
Medical professionals may provide opinions about expected treatment needs.
Similarly, economic specialists may evaluate projected earning losses when necessary.
The specific evidence required depends on the nature of the claim.
Common Mistakes When Documenting Accident-Related Losses
One common mistake is failing to retain receipts for accident-related expenses.
Another is assuming that every financial difficulty following an accident necessarily resulted from the injury.
Some individuals also overlook the distinction between current expenses and projected future costs.
Incomplete employment records can make lost-income calculations more difficult.
Therefore, maintaining an organized record of financial consequences can support a more accurate evaluation.
Final Thoughts
Economic damages after an accident help address the measurable financial consequences of an injury.
Medical expenses, lost income, reduced earning capacity, and certain future costs may all be relevant, depending on the circumstances.
However, recovering compensation generally requires evidence connecting the claimed losses to a legally responsible party.
Understanding these requirements can help injured individuals document financial changes, recognize important insurance considerations, and make informed decisions about potential personal injury claims.